

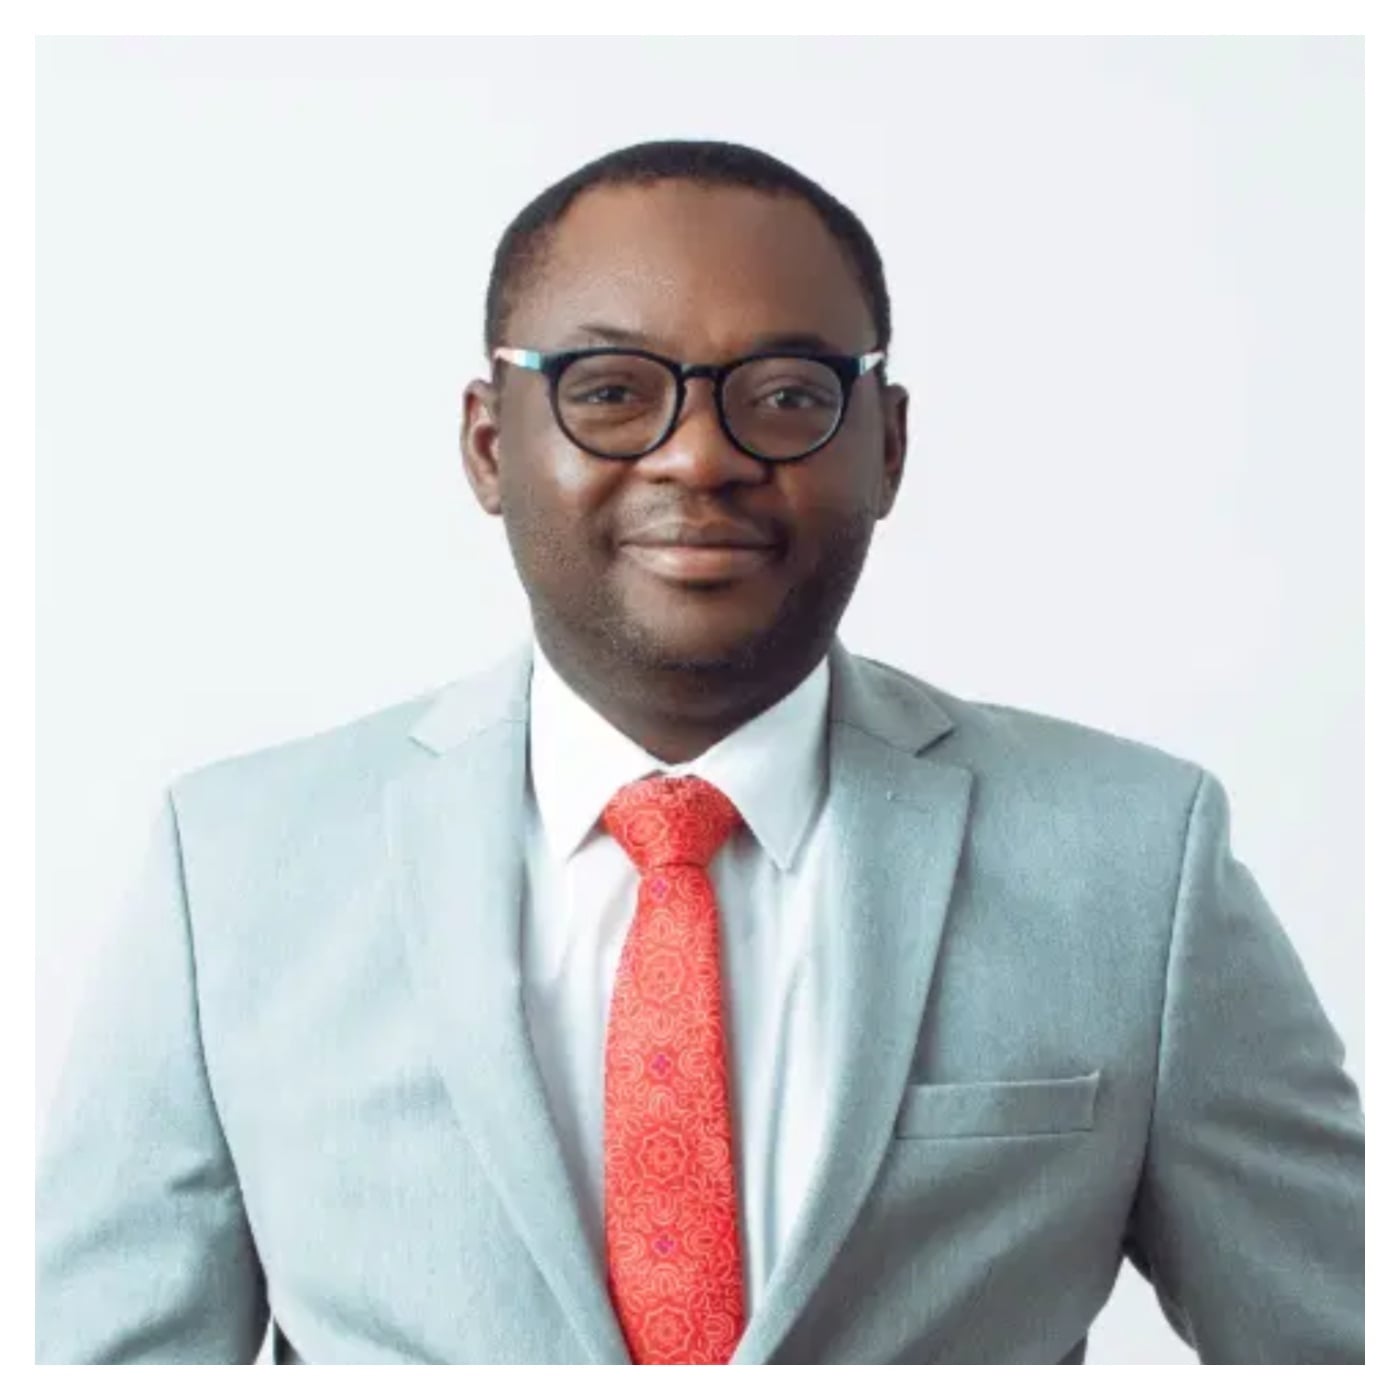
Financial analyst and Professor of Accounting at Lead City University, Ibadan, Godwin Oyedokun, has detailed the implications of Nigeria’s rising debt profile, which stood at N166.79 trillion under President Bola Ahmed Tinubu.
DAILY POST reports that data from the Debt Management Office, DMO, showed that Nigeria’s debt rose by 90.9 percent under Tinubu’s administration, increasing by N87.4 trillion to N166.79 trillion in June 2026.
This means that the country’s debt rose to N166.79 trillion by June 2026, an increase of N7.44 trillion in the second quarter, from N159.35 trillion in March 2026.
The DMO said external debt rose by 28.4 percent to $54.52 billion by June 2026, while domestic debt increased by 55 percent to N91.59 trillion.
Further details of the debt profile indicated that the Federal Government accounted for the bulk of the debt at N152.77 trillion, representing about 91.6 percent.
Reacting, Oyedokun, in an interview with DAILY POST, said the country’s rising debt profile deserves serious attention, particularly because of its implications for the welfare of citizens.
He said that for over 200 million Nigerians, rising debt translates into greater pressure on future public finances, especially as it relates to expenditure on sectors that would benefit ordinary citizens.
“Nigeria’s rising debt profile to N166.79 trillion is a matter that deserves serious attention, particularly because public debt ultimately has implications for the welfare of citizens. The critical issue, however, is not debt accumulation alone, but what the borrowed funds are being used to finance and whether they generate sufficient economic returns to support repayment.
“For over 200 million Nigerians, rising debt can translate into greater pressure on future public finances, especially where debt-service obligations compete with expenditure on education, healthcare, infrastructure, social protection and other essential services. It can also constrain the fiscal space available to respond to future economic shocks,” he told DAILY POST.
According to him, Nigeria needs a stronger debt management culture anchored on measurable outcomes for citizens.
He said every borrowing should be linked to a project or investment capable of boosting productivity.
He added that the focus should shift to demonstrating the benefits Nigerians would derive from the borrowed funds.
“Nigeria therefore needs a stronger debt-management culture anchored on productive borrowing, transparency, accountability and measurable outcomes.
“Every significant borrowing should be linked to projects or investments capable of expanding productive capacity, generating revenue, creating employment and improving economic growth. Borrowing to finance recurrent expenditure without a credible repayment strategy creates a burden that future generations will inherit without necessarily receiving corresponding assets.
“The focus should now shift from asking only how much Nigeria owes to asking what Nigerians have received in return for the debt. Debt can be a useful instrument for development when prudently managed, but it becomes a serious fiscal concern when the growth and revenue generated from borrowed funds are insufficient to service the obligations. The objective should be to ensure that every Naira borrowed today contributes to building an economy capable of generating more income tomorrow,” he told DAILY POST.
